The Deal at a Glance
On July 30, 2025, Nemak announced a definitive agreement to acquire GF Casting Solutions' automotive business from Georg Fischer AG, a Switzerland-based diversified industrials company. The transaction represents one of the largest die casting deals in recent history and marks a pivotal moment for the aluminum casting industry.
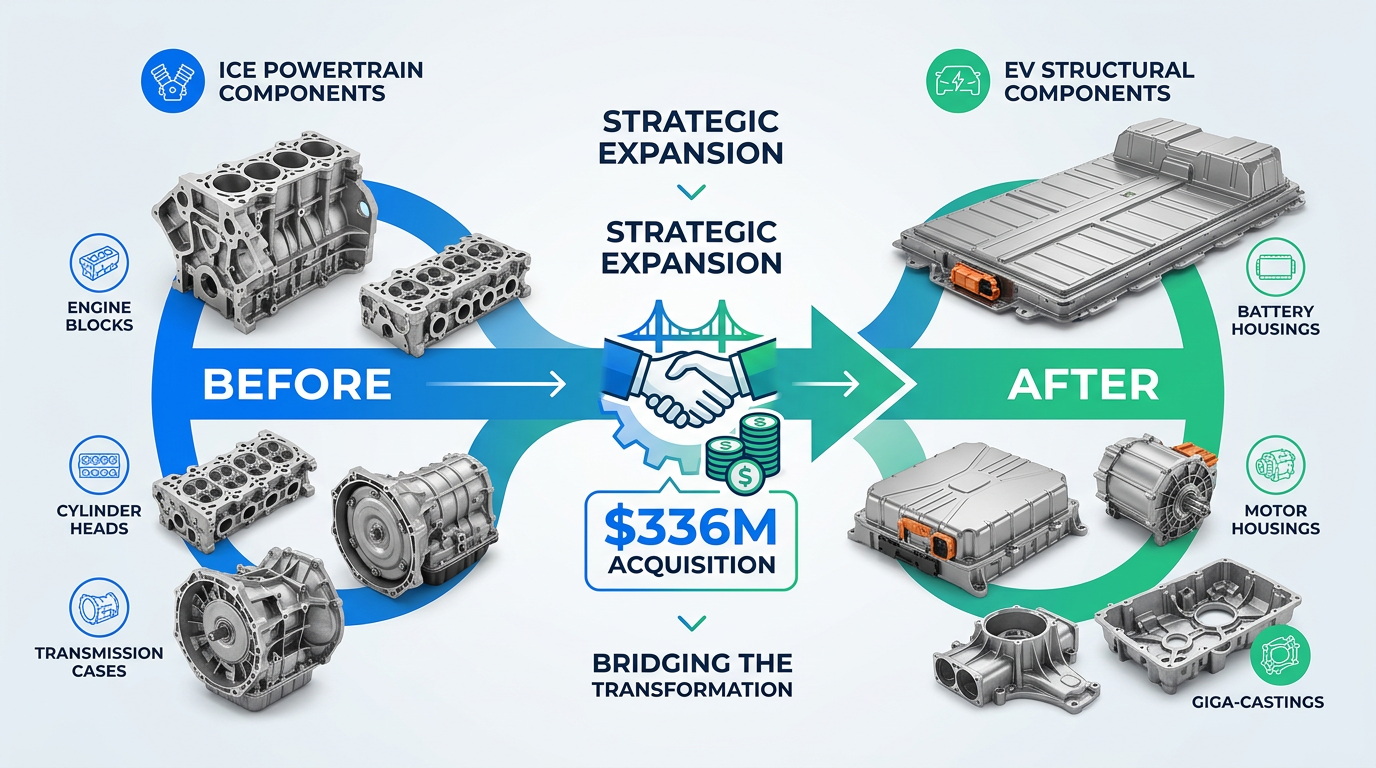
Nemak, Mexico's leading manufacturer and the world's largest aluminum die caster by capacity, will pay a total of $336 million for the acquisition. The deal structure includes $160 million paid upfront, financed through long-term credit lines, with the remaining balance paid over five years through assumed liabilities and deferred payments. The transaction was expected to close in the second half of 2025.
This acquisition represents a strategic move for Nemak to expand beyond traditional internal combustion engine (ICE) powertrain components into the emerging EV structural components market, while simultaneously diversifying its customer base and geographic reach across Europe and Asia.
What Nemak Is Getting
The GF Casting Solutions acquisition brings substantial assets and capabilities to Nemak's portfolio. GF Casting Solutions generates approximately $707 million in annual revenue with adjusted EBITDA of $91 million (based on 2024 figures), demonstrating strong operational performance and profitability.
Key Financial Metrics
Annual Revenue: $707 million
Adjusted EBITDA: $91 million
EBITDA Margin: ~12.9%
Deal Multiple: Approximately 3.7x EBITDA
Global Facilities Network
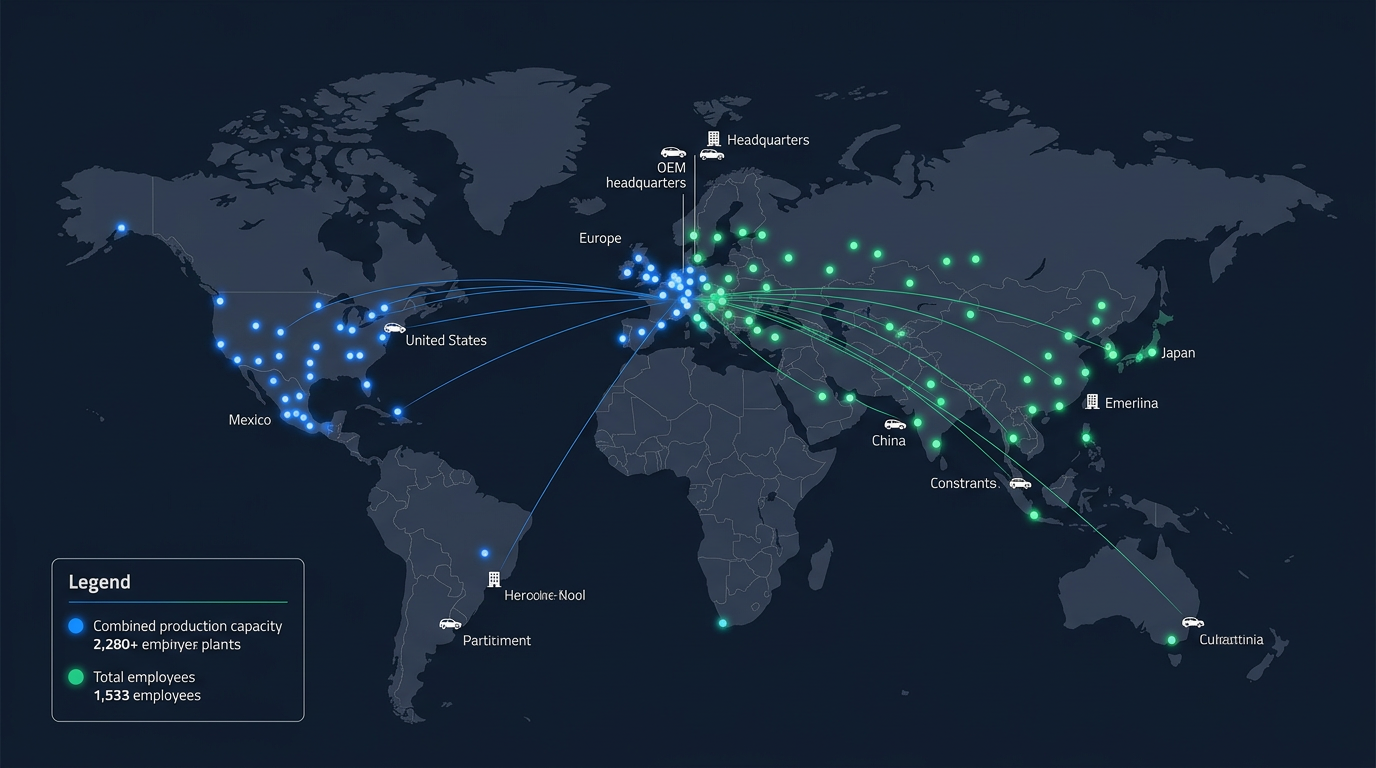
Nemak acquires nine production facilities strategically located across multiple continents, providing geographic diversification and access to major automotive manufacturing hubs:
Austria
Production facility focused on lightweight structural components and premium OEM supply.
Germany
Advanced manufacturing center serving German premium automotive OEMs with specialized HPDC capabilities.
Romania
Cost-competitive production facility supporting Eastern European supply chains.
China
Strategic presence in Asia's largest automotive manufacturing market.
United States
North American manufacturing footprint serving domestic and cross-border OEMs.
Switzerland (HQ)
Headquarters and R&D center for product development and technical innovation.
Workforce and Technical Expertise
The acquisition brings approximately 2,500 skilled employees to Nemak's global workforce. GF Casting Solutions is particularly renowned for its expertise in lightweight structural components, high-pressure die casting (HPDC), and long-standing relationships with premium European original equipment manufacturers (OEMs) including BMW, Mercedes-Benz, Audi, and Porsche.
The Switzerland-based R&D center provides significant technical capabilities in materials science, process optimization, and advanced casting techniques that will strengthen Nemak's innovation pipeline.
Why This Acquisition Matters
This acquisition represents far more than a simple addition to Nemak's production capacity. It marks a fundamental shift in how the world's leading die caster is positioning itself for the automotive industry's electric vehicle transition and evolving manufacturing requirements.
Pivoting Beyond ICE Powertrains
Historically, Nemak built its business around aluminum die casting for internal combustion engine components: cylinder heads, transmission housings, and engine blocks. As automakers shift to electric vehicles, demand for traditional ICE components is declining. GF Casting Solutions' expertise in structural components and lightweighting techniques is essential for EV platforms, where reducing vehicle weight directly translates to increased driving range and improved efficiency.
Diversifying the Customer Base
GF Casting Solutions serves premium European OEMs including BMW, Mercedes-Benz, Audi, and Porsche, all aggressive in their EV transition strategies. These relationships provide Nemak with direct access to high-volume electric vehicle platforms and the opportunity to supply critical structural castings as these vehicles move to production.
Adding High-Pressure Die Casting Capabilities
HPDC (High-Pressure Die Casting) is particularly suited for complex structural components and the intricate part geometries required for EV chassis and battery enclosures. GF Casting Solutions' advanced HPDC equipment and expertise position Nemak to compete effectively for next-generation EV component contracts.
Geographic Expansion
The acquisition significantly expands Nemak's European and Asian manufacturing footprint. With facilities in Austria, Germany, and Romania, Nemak can now serve European OEMs with lower logistical costs and faster delivery times. The China facility provides critical access to the world's largest EV market.
Positioning for the Giga-Casting Era
Tesla's introduction of structural battery pack castings (where the entire vehicle structure is a single aluminum casting) has sparked an industry-wide race to develop giga-casting capabilities. These massive castings require specialized equipment costing tens of millions of dollars. By acquiring GF Casting Solutions' technical expertise and existing facilities, Nemak can invest in giga-casting equipment with a proven customer base already committed to these technologies.
Impact on the Competitive Landscape
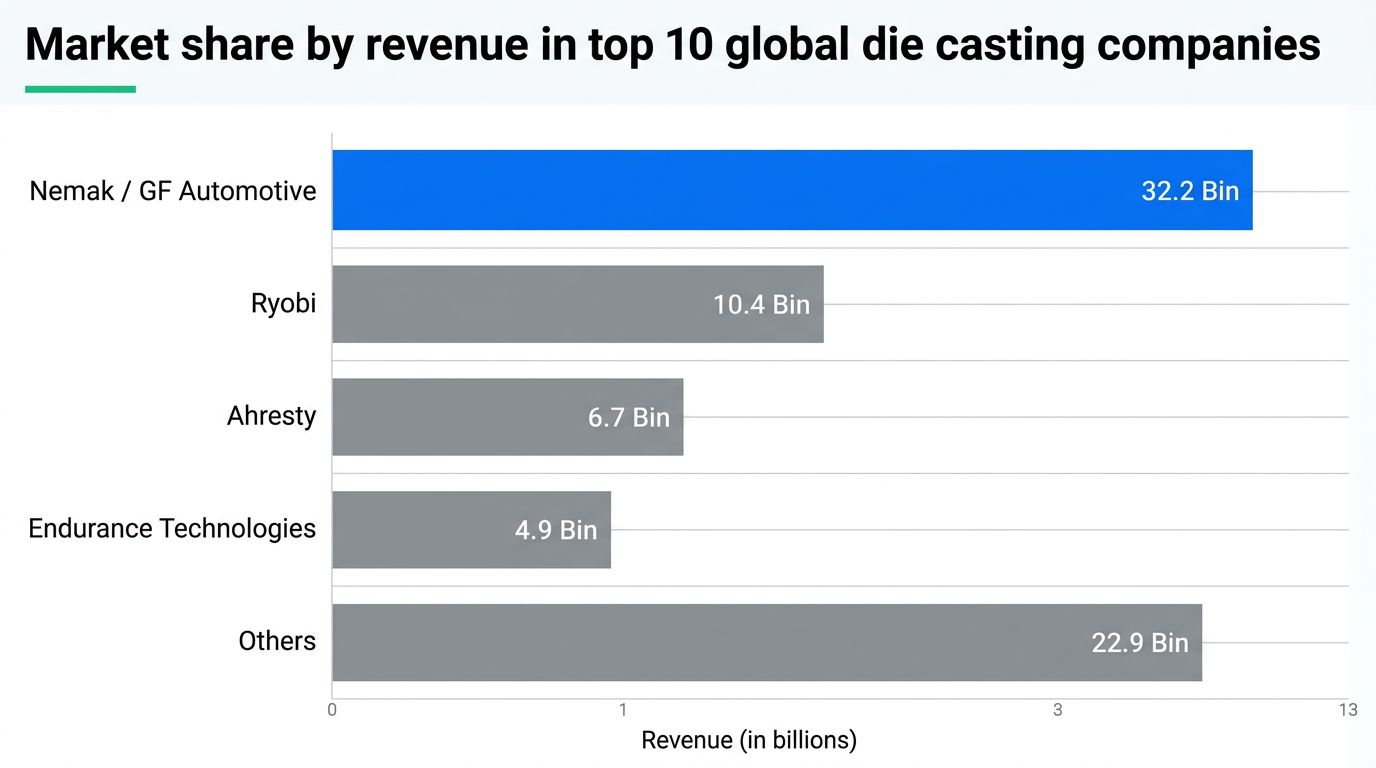
Before this acquisition, Nemak already held approximately 13% of the global aluminum die casting market share, making it the clear market leader. With the addition of GF Casting Solutions' $707 million in annual revenue, Nemak's market position becomes even more dominant.
Global Market Share Implications
Nemak: ~13% (post-acquisition position strengthened)
Ryobi (Japan): ~9%
Ahresty (Japan): ~5%
Dynacast: ~4%
The Consolidation Trend
Nemak's acquisition of GF Casting Solutions is not an isolated event. The die casting industry is undergoing significant consolidation as manufacturers prepare for the capital-intensive EV transition. In March 2025, Sandhar Technologies announced the acquisition of Sundaram-Clayton's aluminum die casting business, further consolidating the industry and reducing the number of independent players.
These mega-deals signal a broader industry trend: smaller, independent die casters are increasingly under pressure to either specialize in niche markets, merge with larger competitors, or risk being squeezed out of supply chains as OEMs consolidate their supplier bases around fewer, larger, more capable casting houses.
Competitive Implications
The gap between the industry leader (Nemak) and second-tier competitors (Ryobi, Ahresty, Dynacast) has widened significantly. This market concentration means:
- OEMs will have fewer casting supplier options for large-volume programs
- Negotiating leverage shifts toward larger casters with diversified capabilities
- Smaller regional players must develop specialized expertise or exit the market
- Technology investment and R&D spending will concentrate among top-tier suppliers
What This Means for Manufacturers
Die casting manufacturers operating across the value chain, from Tier 1 suppliers to Tier 2 and Tier 3 manufacturers, and independent specialty shops, need to reassess their strategic positioning in light of industry consolidation.
Strategic Recommendations for Die Casting Manufacturers
For Tier 2/3 Manufacturers
Consider niche specialization in high-complexity castings, secondary operations, or industry verticals where you can establish competitive advantages. The general-purpose casting business is consolidating; the future belongs to specialists.
For Independent Shops
Explore partnerships, strategic alliances, or mergers with similar-sized competitors. Standalone operations will struggle to compete for large OEM contracts requiring multi-facility support and advanced R&D capabilities.
For All Manufacturers
Invest in non-automotive applications. Defense, aerospace, medical device, and industrial markets remain fragmented with accessible opportunities for quality-focused, specialized shops.
Market Opportunities and Threats
Threats
- Supplier Consolidation: Fewer casting options mean less leverage in negotiations with OEM customers
- Scale Requirements: Large OEM programs increasingly require suppliers with multi-facility, multi-country operations
- Capital Investment: Giga-casting and advanced EV component capabilities require tens of millions in equipment investment
- Technology Demands: Quality standards and advanced material requirements continue to increase
Opportunities
- Secondary Operations: Large casters outsource finishing, machining, heat treatment, and assembly work to specialists
- Specialized Markets: Defense, aerospace, marine, medical, and industrial applications remain accessible for quality shops
- EV Transition Support: Emerging manufacturers and startups need casting suppliers; established relationships with legacy OEMs are not yet locked in
- Supply Chain Diversification: Some OEMs are creating backup suppliers for critical components, creating opportunities for secondary sources
Bargaining Power Shift
Historically, OEMs sourced aluminum castings from multiple suppliers, creating competitive pressure that benefited automotive manufacturers through lower prices. As the industry consolidates around fewer, larger players like Nemak, the bargaining relationship inverts. Nemak's expanded capabilities and market position mean it will have stronger negotiating leverage with OEM customers. This is a shift that smaller competitors must account for in their long-term planning.